Interest Rates Go Up
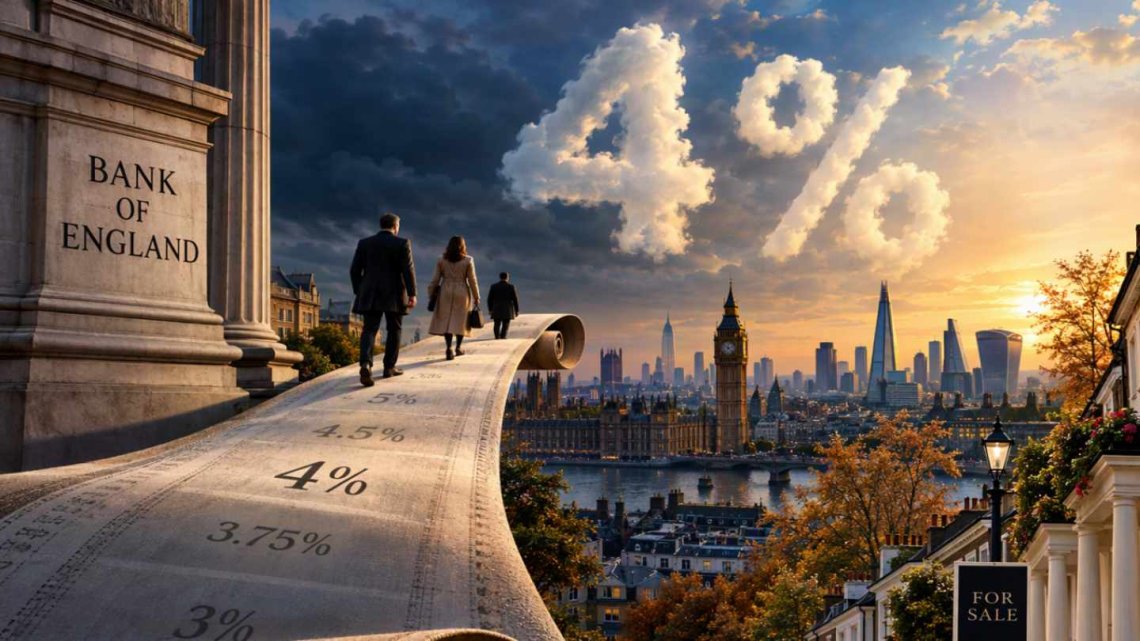
Interest rates are rising again, inflation remains above target and borrowing costs are likely to stay elevated. What does the Bank of England's latest move mean for London's housing market and those looking to buy, sell, rent or invest?
The Bank of England's decision to raise the base rate to 4% marks an important moment for London's property market. While the increase itself is modest, the message behind it is more significant: inflation remains a concern.
The move comes as London's housing market navigates a complex mix of pressures. Mortgage rates remain close to 6%, rental supply is constrained and demand for well-located homes continues to outstrip availability in many parts of the capital.
Inflation stood at 3.5% in September, well above the Bank's 2% target. Higher energy and fuel costs, driven by the impact of the Iran war, have contributed to renewed inflationary pressure, alongside broader domestic price pressures. Faced with that backdrop, policymakers have opted for tighter monetary policy rather than risk inflation becoming more entrenched.
Buyers Face a More Disciplined Market
For buyers, much of the practical impact had already begun to emerge before today's announcement. Mortgage lenders had spent recent weeks adjusting pricing in anticipation of a possible rate increase, with average two-year and five-year fixed mortgage rates already sitting at around 6%. As a result, much of today's decision is likely to have been reflected in existing mortgage pricing, although some lenders may continue to review their products in response to the Bank's latest move.
The effects will be felt most immediately by borrowers on tracker mortgages, whose monthly repayments typically rise in line with changes to the Bank Rate. Homeowners on standard variable rates may also see their borrowing costs increase, depending on how individual lenders respond. Meanwhile, many households coming to the end of fixed-rate deals are continuing to face a sharp jump in repayments compared with the ultra-low rates available several years ago, even if today's increase was largely anticipated by the market.
For prospective buyers, the effect may be felt more through confidence and expectations. Those who had hoped that borrowing costs had peaked, or that interest rates would begin to fall in the near term, may now need to reassess their assumptions. Affordability remains a key consideration, particularly for those relying heavily on mortgage finance, and purchasers are increasingly focused on value, long-term costs and overall financial resilience.
| Feature - scroll to continue with content... |
| continue reading article... |
Sellers Need Realistic Expectations
For sellers, the environment remains one where accurate pricing matters. Demand continues to exist across much of London, particularly for well-presented homes in desirable neighbourhoods, but buyers are taking longer to make decisions and are more willing to negotiate than they were during the era of ultra-low borrowing costs.
Properties launched at realistic prices continue to attract attention. Those that are priced too ambitiously often face greater scrutiny and longer marketing periods.
London's Rental Market Remains Under Pressure
The capital's rental sector faces a different challenge. Average advertised rents in London have reached record highs, while the supply of available rental properties remains limited. Demand remains robust, creating intense competition for many homes that come to market.
For tenants, affordability pressures are likely to remain a defining feature of the market. For landlords, higher borrowing costs may increase financial pressures, although constrained supply continues to provide support for rental values across many parts of London.
| Feature - scroll to continue with content... |
| continue reading article... |
What Happens Next?
With rates now at 4%, attention is already beginning to shift from today's decision to what comes next.
Inflation remains above the Bank of England's 2% target, while the wider economy has shown signs of slower growth. That leaves policymakers attempting to balance two competing risks: allowing inflationary pressures to persist for longer than expected, or tightening monetary policy to the point where economic activity and consumer spending weaken unnecessarily.
Prior to today's decision, market expectations were divided over the future path of interest rates. However, many economists and financial markets now anticipate the possibility of at least one further increase during the first half of 2027 if inflation proves more persistent than the Bank currently expects.
In its latest assessment, the Bank highlighted the impact that higher energy prices and wider global tensions have had on inflation, noting that Consumer Prices Index (CPI) inflation has risen to 3.5% and is expected to increase further in the coming months, peaking at around 5% in 2027 before gradually returning towards target over the medium term.
Explaining the decision to raise rates to 4%, Andrew Bailey, Governor of the Bank of England, said the move "should not be seen as the first of an inevitable long sequence of hikes", stressing that future decisions will depend on incoming economic data, inflation trends and developments in the wider global economy.
However, the Bank's updated inflation forecasts and Mr Bailey’s comments on energy-driven price pressures have led some economists to conclude that further rate rises remain a distinct possibility should inflationary pressures prove more persistent than currently anticipated.
Market Driven by Fundamentals
For London's property market, today's increase is unlikely to represent a dramatic turning point. Rather than signalling either a boom or a downturn, it reinforces a trend that has been developing for some time: a market increasingly driven by fundamentals rather than expectations of ever-cheaper borrowing. Employment, earnings growth, housing supply and local demand are likely to remain key influences on market activity.
After navigating Brexit, the pandemic, the mini-Budget disruption of 2022 and multiple shifts in borrowing costs, London's property market has repeatedly demonstrated resilience. Today's decision does not alter that underlying picture. It does, however, reinforce a new reality for buyers, sellers, renters and landlords alike: the era of exceptionally cheap money has passed, and decisions are once again being made in a higher-rate world.
This article is intended for general information purposes only and does not constitute financial, mortgage, investment, legal or tax advice. Property market conditions, interest rates and government policies can change and may affect individual circumstances differently. Readers should seek independent professional advice from a qualified financial adviser, mortgage broker, solicitor or tax specialist before making property or financial decisions. While every effort has been made to ensure accuracy at the date of publication, no warranty is given regarding the completeness or ongoing accuracy of the information contained in this article.