Average Five-Year Mortgage Rates Reach Six Percent

Mortgage rates are back in the headlines, with the average five-year fixed residential mortgage rate reaching 6.00% on 5 October 2026, its highest level in around three years. According to Moneyfacts, the average two-year fixed rate stood at 5.98%.
Mortgage rates are back in the headlines, with the average five-year fixed residential mortgage rate reaching 6.00% on 5 October 2026, its highest level in around three years. According to Moneyfacts, the average two-year fixed rate stood at 5.98%.
For anyone thinking about buying or selling a London property, those figures may sound concerning. However, they do not necessarily mean that moving plans need to be put on hold.
Importantly, 6% is a market average, not necessarily the mortgage rate an individual buyer will pay. At the time of writing, mortgage products below the 6% market average remain available, depending on individual circumstances and loan-to-value.
Why Are Mortgage Rates Rising?
Although the Bank of England kept Bank Rate at 3.75% on 17 September, fixed mortgage rates are also influenced by wider financial markets.
Moneyfacts reports that fixed mortgage rates have been rising amid increases in swap rates, which are used by lenders when pricing mortgages, with higher wholesale funding costs also putting pressure on rates.
Higher and more volatile energy prices have also added to inflation concerns. The Bank of England reported that UK CPI inflation had risen to 3.1% in August and was likely to rise further over the coming quarters.
For London buyers, where mortgage amounts can be substantial, changes in borrowing costs can make a noticeable difference to monthly repayments.
| Feature - scroll to continue with content... |
| continue reading article... |
Buying in London? Preparation Matters
If you are actively looking for a home, understanding what you can comfortably afford at today's rates is an important first step.
Speaking to a suitably qualified mortgage adviser can help you understand the options available based on your individual circumstances.
From a property perspective, keeping some flexibility around your budget can leave you better prepared when the right home comes along.
Above all, don't let the headline 6% figure discourage you before exploring your individual position. At the time of writing, products below the market average remain available to some borrowers, subject to individual circumstances and eligibility.
Selling? Getting the Price Right Is Key
Today's buyers are understandably more conscious of affordability.
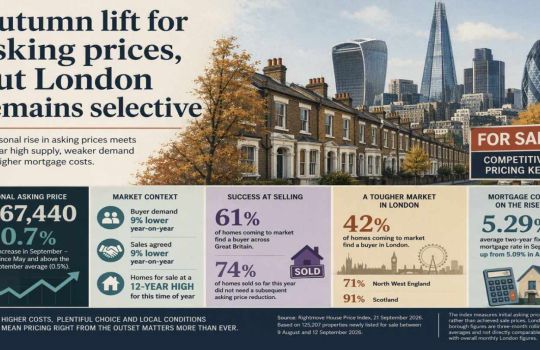
Zoopla estimates that higher mortgage rates have increased repayments for an average UK buyer by around £150 a month compared with the start of 2026, based on its stated mortgage assumptions. Its September House Price Index also reports that buyers are becoming more selective.
For London sellers, this makes realistic pricing from the outset particularly important. Zoopla notes that sellers who price realistically, taking account of demand in their local market, can still find buyers relatively quickly.
A well-presented property brought to market at the right price can stand out to serious buyers. Equally, understanding the strength of an offer, including the buyer's financial position and whether they have a property to sell, can be just as important as the offer itself.
| Feature - scroll to continue with content... |
| continue reading article... |
What If You're Remortgaging?
If your existing fixed-rate deal is approaching its end, it may be sensible to explore your options early with a suitably qualified mortgage adviser.
HomeOwners Alliance advises homeowners whose current mortgage deal ends within the next six months to review their options.
Rather than trying to predict precisely where mortgage rates will go next, the priority should be understanding the options available to you and what you can comfortably afford.
A Changing Market Still Creates Opportunities
Higher borrowing costs are making buyers more selective, but demand for homes remains. Zoopla reports that buyers have become more cautious about where they buy and how much they are prepared to offer.
For buyers, being financially prepared can put you in a stronger position when the right property comes along. For sellers, understanding your local market and setting a realistic asking price from the outset is increasingly important.
In a changing market, good preparation, sensible pricing and experienced local advice can make all the difference.
Sources & Further Reading
- Moneyfacts mortgage market data, reported 5 October 2026: Mortgage rates reach 6%
- Bank of England, 17 September 2026: September Monetary Policy Summary and Minutes
- Zoopla, 1 October 2026: House Price Index: September 2026
- HomeOwners Alliance, updated 5 October 2026: Mortgage Rate Predictions 2026
Mortgage information in this article is provided for general information only and does not constitute financial advice. Mortgage rates, products and eligibility can change and will depend on individual circumstances. You should seek advice from a suitably qualified mortgage adviser before making financial decisions. Mortgage and market information correct at 6 October 2026.