Your First Home: Solving first time affordability?
30 Sep 2026
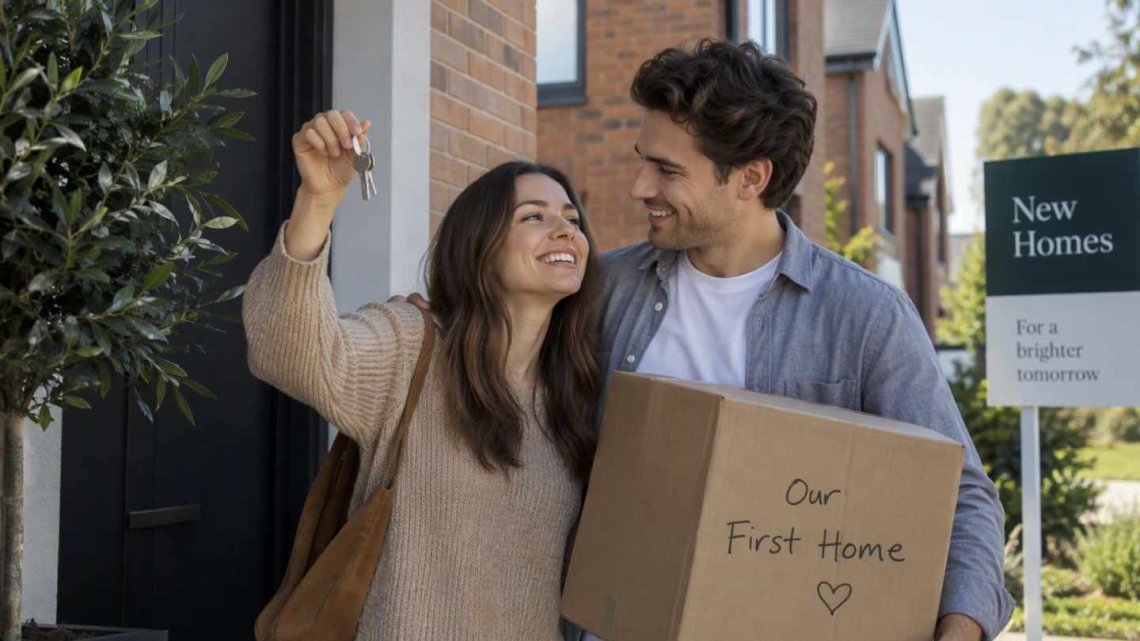
Two first-time buyers holding keys and a moving box outside a newly built home

The Government’s proposed 2.5 per cent deposit scheme could bring home ownership closer for first-time buyers struggling to accumulate substantial savings. But a revival of the equity-loan model also resurrects an old question: does helping buyers ultimately make homes more affordable?

For aspiring homeowners, there is a particular frustration in earning enough to contemplate a mortgage while never quite accumulating the deposit needed to secure one.

The Government’s proposed Your First Home scheme is designed to tackle precisely that problem. Due to be confirmed at the Budget on 28 October, it would allow eligible first-time buyers in England to purchase participating new-build homes with a deposit of just 2.5 per cent, supplemented by a 20 per cent government equity loan with an initial interest-free period.

It is an eye-catching proposition, particularly for renters struggling to save while meeting housing costs. But the implications are more complicated than the headline suggests.

The Government says the policy is intended to tackle the deposit barrier for first-time buyers who would otherwise be unable to afford their first home.

Halving the deposit

A hypothetical £425,000 purchase illustrates the mechanics. A 2.5 per cent deposit would be £10,625. A 20 per cent government equity loan would contribute £85,000, leaving a mortgage of approximately £329,375.

By comparison, a conventional 95 per cent mortgage would require a £21,250 deposit and borrowing of £403,750.

The £425,000 figure is illustrative rather than a proposed scheme limit. Local property-price caps and household income limits are planned, but their levels have yet to be announced.

That distinction will be particularly important in London, where reducing the deposit hurdle does not necessarily solve the underlying problem of high purchase prices. Buyers will still have to demonstrate that they can afford the mortgage and meet lenders’ criteria.


Feature - scroll to continue with content...

continue reading article...

Help to Buy revisited

The architecture inevitably recalls Help to Buy. Introduced in 2013, that scheme also used government equity loans to assist purchasers of new-build properties. Official figures show that 387,195 homes were purchased using Help to Buy equity loans by the time the scheme closed in 2023, including 328,346 purchases by first-time buyers.

Its legacy, however, offers lessons for its successor.

A Government-commissioned evaluation published this month concluded that Help to Buy supported home ownership and housing supply, but identified considerable regional variation. Among almost 6,000 customers surveyed, 54 per cent said they could have bought without the scheme, suggesting that some government support went to households that did not require it.

There was also evidence that the scheme affected prices in already expensive markets.

That presents ministers with a familiar dilemma: assistance can increase buyers’ purchasing power, but unless housing supply responds sufficiently, some of that additional capacity risks being reflected in prices.


Feature - scroll to continue with content...

continue reading article...

The equity question

Another crucial detail concerns the Government’s 20 per cent stake.

This is an equity loan, not a grant or discount. The precise repayment mechanism, length of the interest-free period and any subsequent charges under Your First Home have yet to be detailed.

Under Help to Buy, the amount ultimately repayable reflected movements in the property’s value. It should not be assumed that Your First Home will adopt identical terms. This is one of the important details to watch when the Budget provides the scheme’s financial framework.

Your First Home will also sit alongside existing assistance. The permanent Mortgage Guarantee Scheme already supports mortgages requiring deposits as small as 5 per cent, while First Homes provides qualifying purchasers with discounted properties. The Treasury has also consulted on replacing the Lifetime ISA with a new First Time Buyer ISA.

For buyers shut out principally by the difficulty of accumulating a deposit, Your First Home could make a meaningful difference. For those prevented from buying by high prices relative to earnings, the equation is less straightforward.

The real test on 28 October will therefore be not simply how little buyers need to save, but whether the scheme can improve access to home ownership without inadvertently adding further pressure to the prices they are trying to afford.

This article is for informational purposes. Always seek professional advice before making any property or financial decisions. The views expressed in this article are opinion-based commentary intended to explore potential market outcomes. Housing market performance is influenced by a wide range of factors including interest rates, mortgage availability, economic growth, employment levels, taxation, housing supply, and consumer confidence. Actual market developments may differ from the scenarios discussed. Always seek professional advice before making any property or financial decisions.
Why Choose Fuller Gilbert?

With a passion for property & a commitment to delivering exceptional service, Fuller Gilbert & Company estate agent provides a comprehensive property sales, lettings and management service, with emphasis on quality, transparency and customer satisfaction.Whether you’re buying, selling, renting or investing, Fuller Gilbert combines in-depth local knowledge with a tailored approach to ensure every transaction is smooth and successful.

Get in touch

For more information about Fuller Gilbert & Company, or to discuss your property requirements, Please call 020 7581 0154, email: info@fullergilbert.co.uk or send a message via the contact form on our contact page.

Similar Articles
Surreal illustration of the London property market showing the Bank of England, Westminster and the City skyline beneath a cloud-shaped 4% interest rate symbol.
Interest Rates Go Up

Fuller Gilbert takes at look at what the 4% Base Rate Means for London's Property Market.

05 Nov 2026
Impressionist-inspired image featuring the exterior of a house being painted
Should You Fix It Before You Sell?

Deciding which home repairs are worth making before marketing your property could save you time and money

04 Nov 2026
Cubist-style landscape illustration featuring the Chancellor's iconic red Budget box at the centre of the composition, surrounded by geometric interpretations of 11 Downing Street, the Palace of Westminster, Big Ben, London residential property, house keys, financial charts and pound symbols. Autumn colours of red, gold and orange create a striking visual representing the relationship between government policy, housing and the London property market.
Autumn 2026 Budget Analysis

The key housing, planning and property tax measures announced and what they mean for London's property market.

28 Oct 2026
Pop art-style illustration for an Autumn Budget 2026 property article, featuring the Chancellor's iconic red Budget box in the foreground, the entrance to 11 Downing Street, and the London skyline including the Houses of Parliament and Big Ben. Bold comic-book colours and graphic design elements convey themes of politics, housing policy and the London property market
Autumn Budget 2026 - London Property Preview

Fuller Gilbert explores how the upcoming Autumn Budget 2026 could affect London's property market...

27 Oct 2026
Surreal London property landscape combining Wimbledon greenery, Kensington and Chelsea architecture and the central London skyline.
Autumn property bounce meets cautious reality

Asking prices have rebounded after a subdued summer, but official sales data suggest London’s housing market remains finely balanced.

22 Oct 2026
Property sold board outside a house
Average Five-Year Mortgage Rates Reach Six Percent

Discover what changing borrowing costs could mean for London property buyers and sellers.

06 Oct 2026
London terraced houses and skyline illustrating rising asking prices, increased supply and a more selective property market.
UK Asking Prices Rise as London Market Stays Cautious

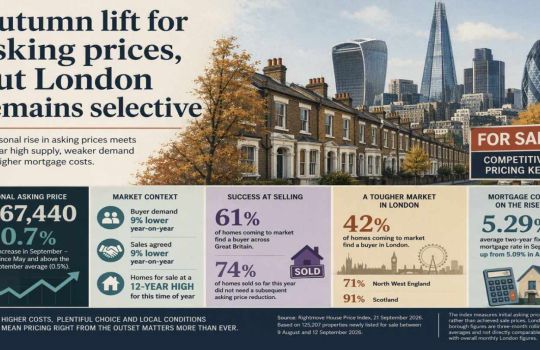
UK asking prices rose 0.7% in September, but plentiful supply, weaker demand and higher mortgage rates keep London’s property market price-sensitive.

26 Sep 2026
Estate agent-style property board displaying the text “London: A New Property Chapter” outside a row of elegant London townhouses, with the River Thames, St Paul’s Cathedral, The Shard and the City of London skyline visible in the background at sunset.
London Property Market Reconfiguration?

More homes, more choice and more realistic pricing are reshaping the capital's housing market

19 Aug 2026
Luxury property-themed board game illustration showing London homes, title deeds, keys and a broken transaction chain representing the risks of a property chain.
Chain Reaction

Why Your Dream Home May Depend on a Stranger's Sale

11 Aug 2026
A sunlit London townhouse stands ready for sale on a warm summer day, with an inviting open front door, manicured garden and stylish outdoor seating in the foreground. A striped deckchair, sun hat and woven beach bag evoke the relaxed pace of the holiday season, while London's iconic skyline rises in the background. The image captures the article's theme of using the quieter summer months to prepare a property for a successful autumn sale, blending lifestyle, aspiration and urban living in a bright, welcoming scene.
Sun, Sand… and Sold?

Why summer may be the smartest season to prepare your home for an autumn sale

03 Aug 2026
Return to Fuller News
Request a Valuation
Valuation Type
About You
Property to be Valued
Your Contact Details
Additional Information
Preferred Time of Day *
By submitting this form, you agree that we may contact you about your enquiry using the details you have provided.
South Kensington Office
South
Kensington
Office
South Kensington Office
Wimbledon
Village
Office

Contact Us

Three Bedroom Apartments Willow & Hawthorn
 Wandsworth Common, SW17
3
2
1

A collection of three bedroom new build apartments finished to a high standard throughout with outside space ranging from £99...

£1,000,000 VIEW PROPERTY
Homefield Road
 Wimbledon Village, SW19
1
1
1

Located in the charming and sought-after area of Wimbledon Village, this beautifully presented modern apartment offers a delightfu...

£2,250 PCM VIEW PROPERTY