UK Asking Prices Rise as London Market Stays Cautious
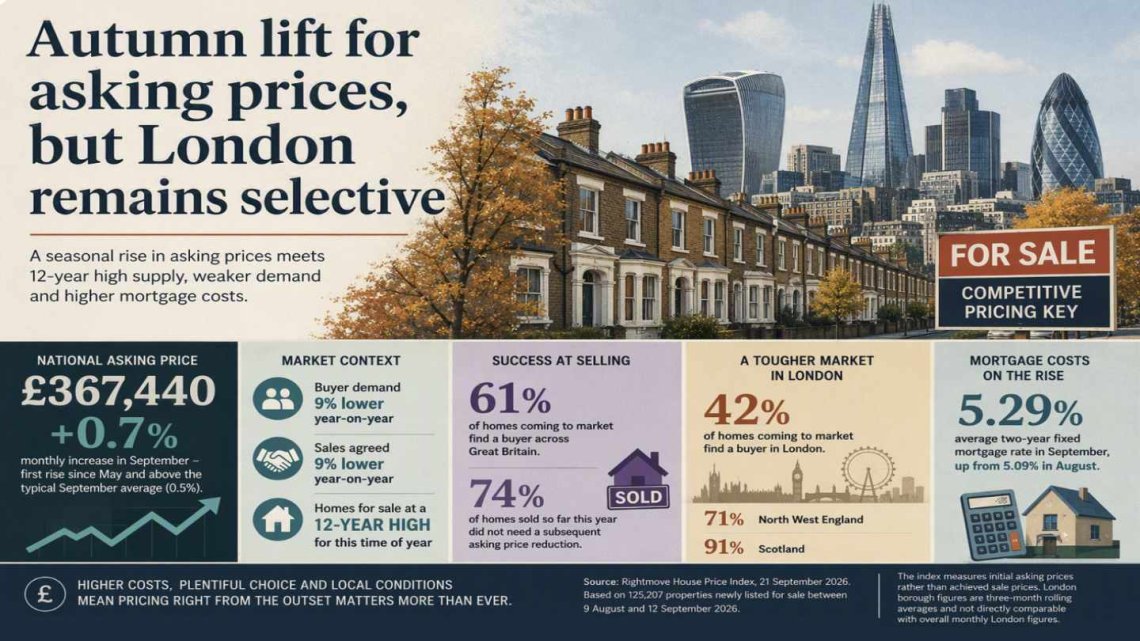
A seasonal rise in asking prices has brought some momentum back to the housing market, but abundant supply, weaker demand and higher borrowing costs are keeping buyers firmly price-conscious, particularly in London.
Britain’s housing market showed tentative signs of renewed activity in September, although the improvement comes against a backdrop of constrained affordability and unusually plentiful supply.
The average asking price of a newly listed home rose 0.7 per cent to £367,440, according to the September 2026 Rightmove House Price Index. The increase, the first since May, was slightly above the 0.5 per cent average September rise recorded over the previous decade. Asking prices nevertheless remain 0.8 per cent below their level a year ago and 2.3 per cent below where they stood at the beginning of the summer.
The figures suggest a seasonal recovery rather than a decisive shift in the market. Buyer demand and agreed sales are each 9 per cent lower than a year ago. Although the flow of newly listed properties is also down, the total stock of homes for sale stands at a 12-year high for this time of year.
For sellers, that abundance of choice has made pricing increasingly consequential. Across Great Britain, 61 per cent of homes coming to market find a buyer. Rightmove’s analysis also found that 74 per cent of homes sold so far this year had not required a subsequent reduction in their asking price.
| Feature - scroll to continue with content... |
| continue reading article... |
London feels the pressure
Conditions appear particularly testing in the capital, where only 42 per cent of homes coming to market find a buyer. That compares with 71 per cent in North West England and 91 per cent in Scotland.
London itself presents a varied picture. Rightmove’s borough data records annual asking-price growth of 2.4 per cent in Haringey and 0.8 per cent in Richmond upon Thames. Elsewhere, asking prices were 5.8 per cent lower in Wandsworth, 5.6 per cent lower in Barnet, 6 per cent lower in Camden and 5.3 per cent lower in Kensington and Chelsea. The borough figures are three-month rolling averages and are not directly comparable with Rightmove’s overall monthly London figures.
Borrowing costs provide a further constraint. The average two-year fixed mortgage rate cited in the index rose from 5.09 per cent to 5.29 per cent, maintaining pressure on household affordability.
September’s increase therefore offers some encouragement without fundamentally altering the character of the market. For sellers, initial pricing and presentation assume greater importance when purchasers can afford to be discriminating. For buyers, increased choice may provide greater scope for negotiation, but financing costs continue to limit purchasing power.
The autumn market may be stirring, but in London especially, the national headline conceals a more fragmented picture. The balance increasingly turns on the merits, pricing and location of the individual property rather than the direction of the wider market.
| Feature - scroll to continue with content... |
| continue reading article... |
Source: Rightmove House Price Index, 21 September 2026. Rightmove’s September index is based on 125,207 properties newly listed for sale between 9 August and 12 September 2026. The index measures initial asking prices rather than achieved sale prices. London borough figures are based on three-month rolling averages and are not directly comparable with the overall monthly London figures.
This article is for informational purposes. Always seek professional advice before making any property or financial decisions. The views expressed in this article are opinion-based commentary intended to explore potential market outcomes. Housing market performance is influenced by a wide range of factors including interest rates, mortgage availability, economic growth, employment levels, taxation, housing supply, and consumer confidence. Actual market developments may differ from the scenarios discussed. Always seek professional advice before making any property or financial decisions.