Autumn Budget 2026 - London Property Preview
As the Autumn Budget approaches, the London property market is watching closely for potential announcements on housing, taxation and the wider economy. This preview examines the proposed Your First Home scheme, the outlook for buyers, sellers and landlords, and the economic factors that could shape London's property market in the months ahead.
A Return to Confidence Amid Economic Uncertainty?
As the Autumn Budget approaches, buyers, sellers, landlords and investors across London are assessing what the Chancellor's announcements could mean for the property market.
While the contents of the Budget have yet to be confirmed, speculation surrounding potential tax changes, housing initiatives and wider economic policy has already influenced market sentiment. Against a backdrop of affordability challenges, elevated borrowing costs and ongoing global uncertainty, many market participants will be looking for greater clarity on the Government's direction of travel.
Among the measures that have been announced ahead of the Budget is the proposed Your First Home scheme, designed to support first-time buyers. However, until the Chancellor delivers the Budget, the scale of any housing measures, tax changes or economic interventions remains uncertain.
This article considers some of the key issues likely to be relevant to the London property market and examines how emerging policy proposals and economic forecasts could influence market activity in the months ahead.
The Your First Home Scheme
One of the most significant housing measures expected to feature in this week's Budget is the formal introduction of the Your First Home scheme.
Based on proposals announced by HM Government, eligible first-time buyers in England may be able to purchase a new-build home with a deposit of just 2.5%, supported by a government-backed equity loan of up to 20%.
For many aspiring homeowners in London, where raising a deposit often remains the greatest barrier to homeownership, the scheme has the potential to improve accessibility for first-time buyers. If introduced in its proposed form, it could also support demand in parts of the lower and mid-market sectors.
However, some housing commentators have cautioned that measures designed to boost purchasing power may place additional pressure on prices unless accompanied by a meaningful increase in housing supply. Whether any such effect materialises would depend on the final structure of the scheme, market conditions and the pace of new housing delivery.
| Feature - scroll to continue with content... |
| continue reading article... |
Residential Sales Market Outlook
The sales market has spent much of the year navigating uncertainty surrounding economic policy, taxation and borrowing costs.
Speculation over Capital Gains Tax changes and other potential property-related measures has encouraged some buyers and sellers to adopt a wait-and-see approach. Recent media commentary has suggested that significant Capital Gains Tax increases may be less likely than previously anticipated, although no final decisions have been confirmed ahead of the Budget.
Should the Budget provide greater policy certainty, it may help improve confidence among buyers and sellers, particularly within London's higher-value markets. However, the extent to which this translates into increased activity remains difficult to predict.
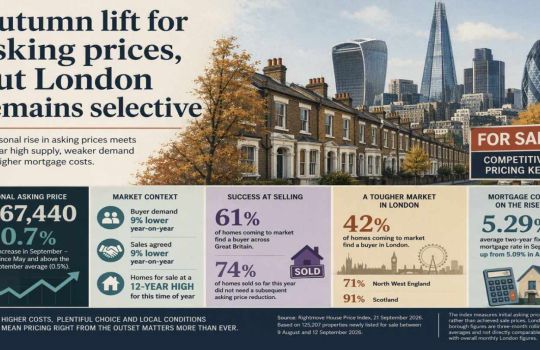
Affordability also continues to represent a significant constraint. Mortgage rates remain materially higher than those experienced during much of the previous decade, and borrowing costs continue to influence buyer behaviour.
While forecasts vary, many market commentators believe house price growth across Greater London is likely to remain relatively modest while affordability remains stretched.
Lettings Market Outlook
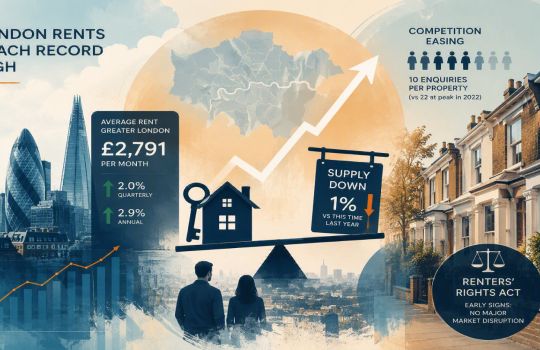
The private rented sector continues to face a well-documented imbalance between supply and demand.
Recent media commentary suggesting that significant Capital Gains Tax increases may be less likely could provide reassurance to some landlords who have been considering reducing or restructuring their portfolios. However, a range of regulatory, taxation and financing considerations continue to influence landlord decision-making.
At the same time, higher mortgage costs have limited access to homeownership for many households, helping to sustain demand for rental accommodation across much of London.
Demand for rental housing continues to exceed available supply in many areas of the capital, a dynamic that many market commentators regard as supportive of rents. However, local market conditions can vary significantly and future rental performance will depend on economic conditions, housing supply and tenant affordability.
Global and Economic Headwinds
Property markets do not operate in isolation. Ongoing geopolitical tensions, including conflicts in the Middle East and Ukraine, continue to contribute to volatility in global energy markets and broader economic uncertainty.
| Feature - scroll to continue with content... |
| continue reading article... |
Inflation and Interest Rates
Higher global energy prices remain a potential risk to the UK's inflation outlook. Forecasts from Oxford Economics suggest that rising fuel and energy costs could push inflation above 4% before gradually easing during 2027, although the precise trajectory will depend on developments in global energy markets and wider economic conditions.
The inflation outlook remains particularly relevant to the property market because it may influence future interest-rate decisions. Oxford Economics has argued that continued inflationary pressures could require the Bank of England to maintain a relatively restrictive monetary stance for longer than previously anticipated.
Future interest-rate decisions remain uncertain and will depend on incoming economic data. However, elevated borrowing costs would be expected to continue weighing on affordability and could influence transaction activity across the housing market.
Fiscal Constraints
The Government is also operating within an increasingly challenging fiscal environment. Rising borrowing costs and pressure on public finances may limit the scope for significant new spending commitments, increasing the importance of maintaining market confidence.
Recent economic analysis suggests the Chancellor's fiscal headroom may have narrowed since the Spring Forecast as a result of higher borrowing costs and weaker growth expectations. As a result, the Budget is likely to involve balancing measures designed to support economic growth with the need to maintain fiscal credibility.
In Summary
As the Autumn Budget approaches, the London property market remains focused on a number of key themes, including housing affordability, taxation, interest rates and economic confidence.
While the proposed Your First Home scheme has attracted considerable attention and recent media commentary suggests some previously anticipated tax changes may be less likely, the final shape of the Budget has yet to be confirmed.
What appears clear is that affordability constraints, borrowing costs and wider economic conditions are likely to remain important influences on the market regardless of the specific measures announced.
For buyers, sellers, landlords and investors alike, the Budget may provide greater clarity on the Government's direction of travel. However, the longer-term performance of London's property market will continue to depend on a combination of housing supply, economic conditions, consumer confidence and interest-rate movements in the months ahead. Until the Budget is delivered, clarity remains in short supply, making informed preparation as important as ever.
Source note: This article draws on publicly available information, economic forecasts and industry commentary, including publications from HM Government, the Office for Budget Responsibility (OBR), the Bank of England, Oxford Economics and KPMG, available at the date of publication.
Disclaimer: This article is based on publicly available information, industry commentary and economic forecasts available at the date of publication. Forecasts and expectations regarding inflation, interest rates, tax policy, government housing initiatives and property market performance are inherently uncertain and may change following the Autumn Budget, subsequent legislation, future Government announcements, or decisions by the Bank of England. The content is provided for general information purposes only and does not constitute financial, investment, tax or legal advice. Readers should seek appropriate professional advice before making property, financial or investment decisions.