To Rent or Buy in 2025?
The decision to rent or buy a home remains one of the most significant financial choices many people face. In 2025, this decision is particularly nuanced due to shifting interest rates, evolving property prices, and changing lifestyle priorities. Whether you're a first-time buyer, a downsizer, or someone weighing up the pros and cons of renting, Fuller Gilbert explores some key factors to help you make an informed choice.
Financial Flexibility: The renting advantage
Renting offers a level of financial flexibility that’s especially appealing in uncertain economic times and enables renters to avoid large upfront costs like deposits, stamp duty, and legal fees. Instead, the primary financial commitment is a predictable monthly rent.
Renters also sidestep the costs of property maintenance and buildings insurance, which for many can significantly reduce financial stress. For those prioritising mobility - whether for career, family, or lifestyle reasons - renting allows for easier relocation at the end of a lease.
Building Equity: The Buying Advantage
Buying a home is often seen as a long-term investment. Monthly mortgage payments contribute to building equity, and if property values rise, so does your net worth.
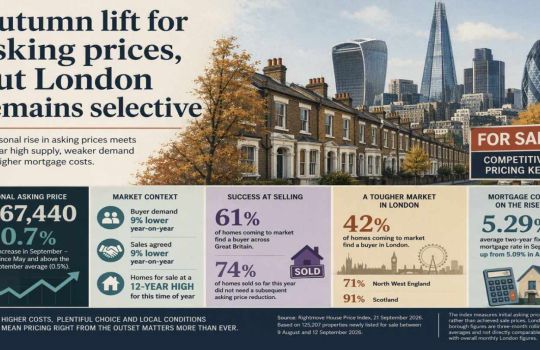
In 2025, interest rates have eased slightly to 4.25%, down from the 5.25% peak in 2023. While still higher than the near-zero rates of the early 2020s, this decline offers some relief to buyers. Fixed-rate mortgages (typically 2–5 years) provide payment stability, though further rate cuts are anticipated later this year. Timing your purchase could impact your long-term costs.
Meanwhile, Zoopla says rental prices have surged by 21% over 3 years, and are forecast to rise by another 3 - 4% in 2025 - especially in high-demand areas like London. This makes long-term renting potentially more expensive than buying in some regions.
Interest Rates and Property Prices in 2025
- Interest Rates: Currently at 4.25%, with potential cuts expected later in the year.
- Property Prices: UK house prices rose by 1% in 2024 according to Rightmove, with a projected 4% increase in 2025.
- Rental Market: Despite a 17% supply increase in the past year (Zoopla), tight supply and strong demand continue to push rents upward, though price-growth is slowing.
For buyers with stable incomes and long-term plans, purchasing now could be a sound investment. However, first-time buyers may still find affordability a challenge, especially in London and the South East.
| Feature - scroll to continue with content... |
| continue reading article... |
Long-Term Financial Goals: Stability vs. Flexibility
Your long-term goals should guide your decision:
- Buying is ideal if you plan to stay in one place, want to build equity, and value cost stability.
- Renting suits those in transitional life stages - early career, frequent relocations, or uncertain future plans. It offers flexibility without the responsibilities of ownership.
Maintenance and Upkeep: Who’s Responsible?
- Homeowners are responsible for all maintenance, from minor repairs to major renovations.
- Renters typically rely on landlords for repairs and upkeep, making it a lower-stress option for those with limited time or funds.
Tax Considerations
By and large there are few, if any, tax reliefs for individual homeowners in the UK. Mortgage interest relief was phased out for most homeowners in the UK in 2020, and is restricted to a very few exceptions (eg: using part of your home exclusively as a business office). However, landlords are able to claim a 20% basic-rate tax credit instead.
Homeowners can still benefit from other incentives, such as the stamp duty relief (e.g. first-time buyer exemptions), but property taxes (like Council Tax) are generally paid by all homeowners, regardless of ownership status. Renters, typically do not receive any tax relief but do avoid the costs associated with property ownership, such as mortgage repayments and maintenance costs.
Overall, homeownership can be financially advantageous in the long term, particularly for higher earners who benefit from the ability to build equity in their property. However, there are no direct tax reliefs on mortgage interest for homeowners.
Making the Right Decision for You
There’s no universal answer to the rent vs. buy debate in 2025. Your decision should reflect your:
- Financial situation - Lifestyle needs - Career plans - Long-term goals
Quick Summary:
- Renting: Lower upfront costs, greater flexibility, fewer responsibilities.
- Buying: Builds equity, offers stability, higher initial and ongoing costs.
Before deciding, assess your personal goals and, if necessary, consult a financial or real estate advisor to ensure your choice aligns with your future.
This article is for informational purposes only and does not constitute financial or legal advice. Always seek professional legal and financial advice before making any property decisions.